Hidden out-of-pocket costs: The line between medical equipment and home modifications.
September 18, 2026 · Kindred Home Support
The DME Coverage Trap: Why Your Walker is Covered But Your Transfer Pole Isn't
Families navigating post-discharge care quickly run into a frustrating wall of bureaucratic logic: the assumption that insurance smoothly covers every device required to safely manage daily life at home.
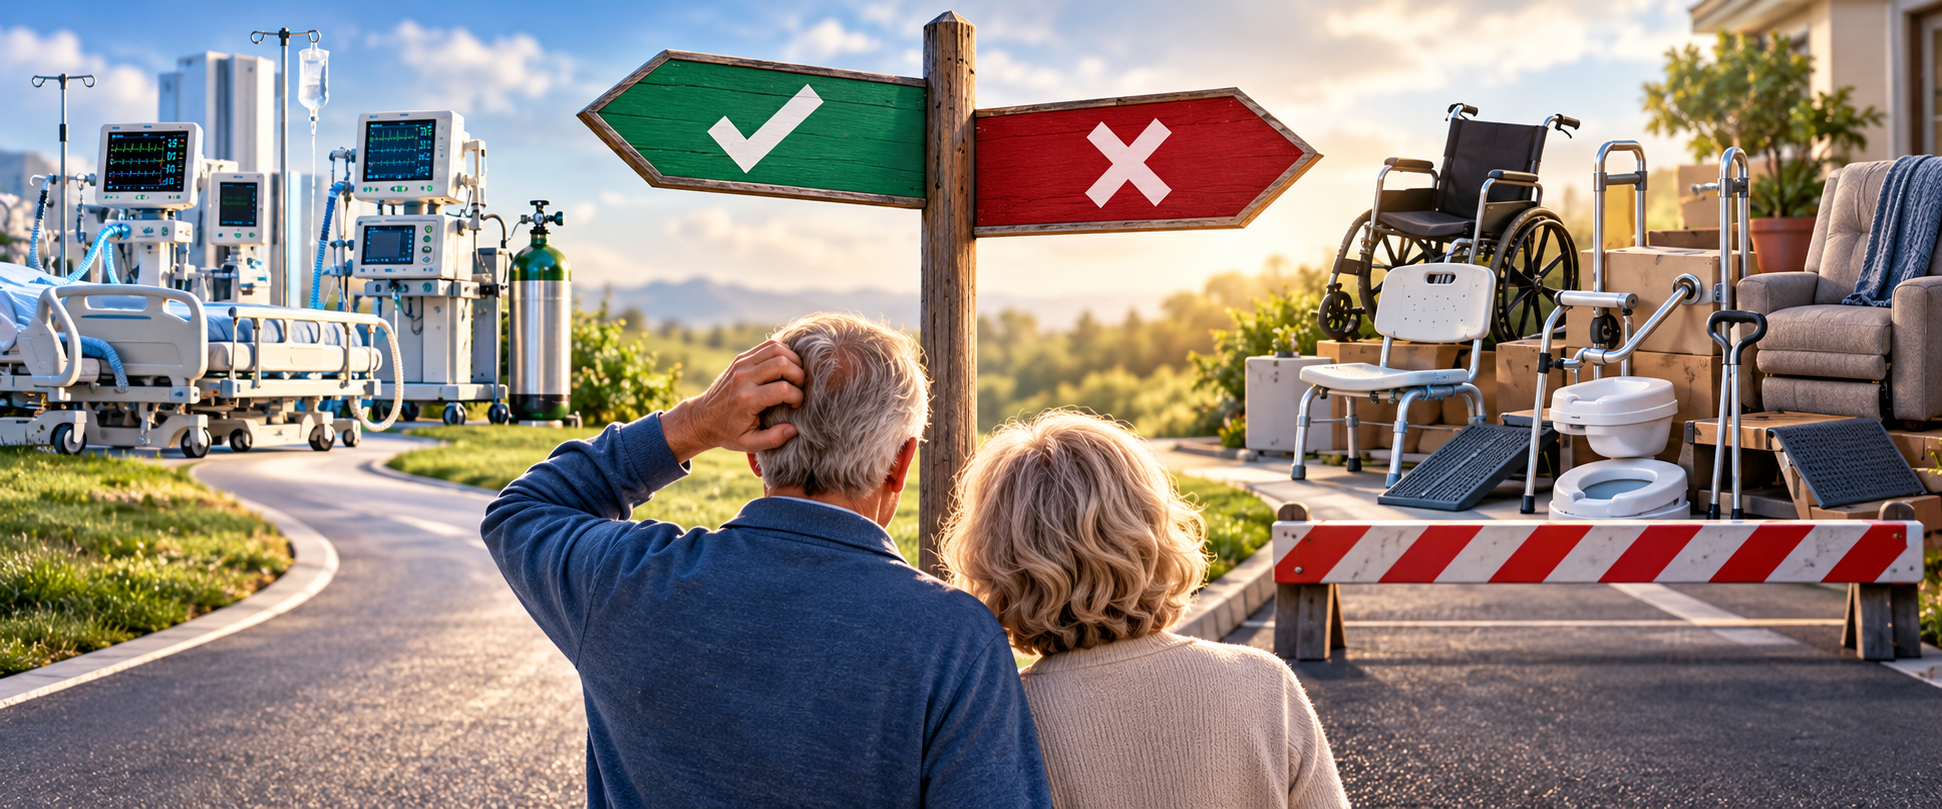
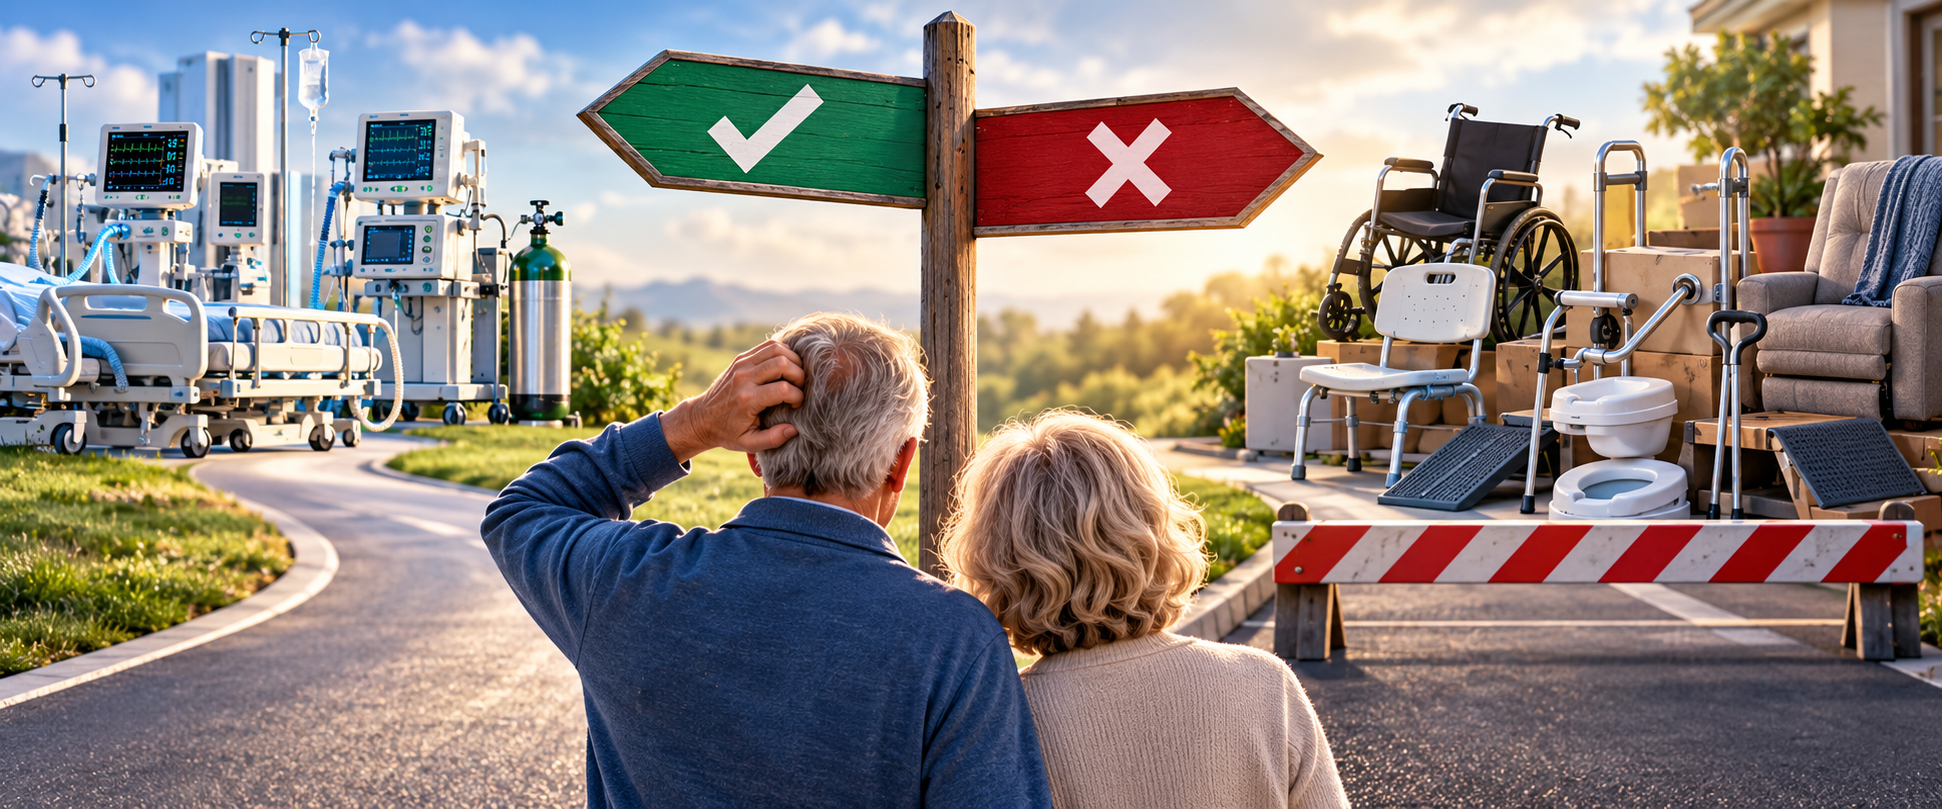
In reality, the line between what qualifies as covered Durable Medical Equipment (DME) and what families must buy entirely out-of-pocket defies common sense. Items that seem critical for basic survival and safety are frequently excluded, while complex clinical machinery sails through approval.
The 3-Year Durability Rule
Medicare Part B covers equipment only if it meets strict federal criteria:
- It must be prescribed by a physician for medical necessity.
- It must be designed for repeated use in the home.
- It must be engineered to last at least three years.
This mechanical definition creates immediate discrepancies in daily routines, separating essential medical machinery from vital environmental safety devices.
What Gets Covered (The Expected)
- Standard walkers, rollators, and manual or power wheelchairs.
- Hospital beds and alternating pressure-relief mattresses.
- Patient lifts and bedside commode chairs ordered for documented immobility.
What Gets Excluded (The Surprising Reality)
- Bathroom Safety Equipment: Standard raised toilet seats, bathtub transfer benches, and wall grab bars are classified as "convenience or home adaptation" items rather than primary DME, leaving families to cover 100% of the cost.
- Home Structural Modifications: Wheelchair ramps, stair lifts, widened doorways, and roll-in showers are categorically excluded from insurance reimbursement, despite being mandatory for safe transfers.
- Transfer Poles and Floor-to-Ceiling Grab Bars: Because they often require tension-mounting or minor structural installation, floor-to-ceiling poles that prevent bedside falls are routinely denied coverage.
- Accessory Add-Ons: Tray tables, storage pouches, and specialized glider brakes for walkers are treated as non-essential accessories and excluded from standard benefit caps.
Bridging the Gap
Relying on standard insurance approvals leaves critical safety gaps during the most vulnerable window of home recovery. While waiting months for prior authorizations or fighting denied claims, families face immediate environmental hazards.
Combining supplemental benefit allowances—such as Medicare Advantage flex cards—with direct, private environmental safety setup ensures the home is secure before the patient ever walks through the door.
Insurance defines medical necessity by the device's mechanical classification, not by the family's daily risk of a catastrophic fall in the bathroom.